Serving Muskoka · Simcoe County · Cottage Country

Cottage and recreational property mortgages, sorted out for you.

Financing a cottage is not like financing a home in town. Lenders care a lot about whether you can get there in the winter, where the water comes from, and whether the place is built to be lived in year round. Some cottages are easy to finance and some take real know-how. I do both, and I know which lenders say yes to what.

25+
Years helping Ontario homeowners
100+
Lenders, from the big banks to private investors
40+
Five Star Google Reviews

Come talk to me if you are looking at

  • ✓ A four season or three season cottage
  • ✓ A seasonal place with no winter access
  • ✓ A waterfront or water access property
  • ✓ A second home for the family
  • ✓ A cottage you plan to rent out part of the year
  • ✓ A place a big bank called recreational and passed on

Why cottages are different

Two cottages, two completely different mortgages.

Here is the thing that catches people off guard. Lenders sort cottages into two buckets, and which bucket yours falls into changes everything. A winterized cottage on a year round road, with a permanent foundation and a proper water source, gets treated almost like a regular home. A seasonal place with no heat, no winter access, or water you can only reach by boat is a much shorter list of lenders and usually a larger down payment.


Most people do not know which bucket their cottage is in until they are already trying to buy it, and that is a stressful time to find out. I can tell you early, often from a few quick questions about the property, so you know what to expect before you make an offer. From there it is about matching the cottage to a lender who is comfortable with it and presenting the file properly.

Who this is for

The kind of properties I help with

Four season cottages

A house sitting on anything from a couple of acres to a hundred, where the land is a big part of what you are buying.

Seasonal cottages

A bit of land, maybe some animals or crops, that is not your full time living. These need lenders who understand the setup.

Waterfront properties

No municipal water or sewer. Common in the country, and something certain lenders want documented before they say yes.alongside your lawyer to keep it moving.

Water access only

Beautiful to live in, trickier to finance. Non-standard construction narrows the list of lenders, but it does not close the door.

Family second homes

Barns, shops, drive sheds, second garages. Whether that value counts toward your mortgage depends entirely on the lender.

Cottages you rent out

If you plan to rent it part of the year, that changes the file. Some lenders are fine with it, and some are not.

What lenders look at

What matters when you finance a cottage

When I take a cottage file to a lender, these are the points that come up almost every time.

Knowing them early is how we avoid surprises.

Year round access

Many lenders cap the acreage they will value. Anything past that may not add to what you can borrow.

Heat and winterization

Whether the road to the property is maintained all year, and who maintains it, can matter to an approval.

The water source

A barn or shop can be a real asset, but not every lender counts it. That difference can move your numbers.

Foundation and construction

A well and septic are normal in the country, but lenders often want proof they are in good working order.

Shoreline and land

Residential, rural, agricultural. How the land is zoned changes which lenders will even look at it.

Whether you will rent it

Renting the cottage out, especially short term, changes how some lenders see the file, so it is best to be upfront.

How it works

Simple, and I stay with you the whole way

STEP 1

Tell me about the cottage

Where it is, how you get there, the heat, the water, and whether it is four season. A few questions tell me a lot.

STEP 2

I match it to the right lenders

I go to the lenders who are comfortable with your kind of cottage and present it so it gets a fair look.

STEP 3

We get you to closing

You get an approval that fits, and I stay on the details right through to the weekend you finally get the keys.

40+ Verified Five Star Google Reviews

Real situations we've helped with.
Mortgage Broker
#M08006998

CONTACT US APPLY NOW

Download My Mortgage App HERE

Meet Anita

Financing is what I love doing

Hello, I’m Anita. Thanks for visiting me online. My team and I absolutely love arranging mortgage financing for people like you; it’s our passion. If you're looking to purchase or refinance your existing home or investment property, I specialize in providing customized solutions for my clients. You've come to the right place!


My goal is to help facilitate your financial goals and find the perfect funding solution to lower the overall cost of borrowing. I keep up to date on global economics to sight the trends that might affect the industry, so you don't have to. It’s always exciting to discuss strategies in our evolving economic climate. Times are tough, and with mortgage guidelines continually changing, it can be a challenge to obtain financing, even for someone with excellent credit and net worth!


I have been happily married for over 40 years, and we're proud parents of two children and eight beautiful grandchildren! I enjoy spending time with family, I'm an avid foodie, and enjoy travelling.

Areas served

Cottage and recreational financing across cottage country

Home base is Orillia, right on the edge of cottage country, and I arrange cottage mortgages

throughout Muskoka, Simcoe County, and the lakes. Most of the work happens by phone, email, and video, so where the cottage is located is rarely a barrier.

Muskoka Gravenhurst Bracebridge Huntsville Orillia Lake Simcoe Lake Couchiching Georgian Bay Kawartha Lakes Severn Ramara Washago Simcoe County Cottage Country
All of BC & Alberta

Common questions

Cottage and recreational mortgage questions

  • Is it harder to get a mortgage on a cottage than a regular home?

    It depends entirely on the cottage. A winterized place on a year round road can be almost as easy as a home in town. A seasonal cottage with no winter access is more specialized and often needs more down. The first step is figuring out which kind yours is.

  • How do lenders decide how hard my cottage is to finance?

    It mostly comes down to whether the place can be lived in year round. A cottage that is winterized, sits on a permanent foundation, has a proper water source, and can be reached on a maintained road all year is treated close to a regular home. A more seasonal place, with no heat or no winter access, needs specific lenders and usually a bigger down payment. I will tell you where your cottage sits.

  • How much down payment do I need for a cottage?

    For a four season cottage it can be similar to a regular home. For a seasonal or water access property, lenders usually want more down. Rather than guess, let me look at the specific cottage so you know the real number before you make an offer.

  • Can I finance a cottage I can only reach by boat?

    Sometimes, yes, though water access properties are the hardest recreational files. The list of lenders is short and the down payment is usually higher, but it can be done with the right one. Send me the details and I will tell you honestly where you stand.

  • Can I get a mortgage on a seasonal cottage with no winter access?

    Often yes. Seasonal cottages are financed all the time, just by a smaller group of lenders who are comfortable with them. It usually means a bit more down, but no winter access on its own does not sink the deal.

  • Does renting out my cottage affect the mortgage?

    It can. If you plan to rent it, especially short term, some lenders are fine with it and others are not. It is best to be upfront from the start so we go to a lender who is comfortable with your plans.

  • My bank called it recreational and turned me down. Can you help?

    Often, yes. A bank passing on a cottage usually means it did not fit their narrow rules, not that no lender will finance it. Cottage and recreational files are a regular part of what I do, so it is worth a conversation before you give up on the place.

Everything, in one place

Other situations I handle

Each of these has its own page that walks through the details in plain language.
RESIDENTIAL

Buying, renewing and refinancing

    PROPERTY TYPES

    Rural, farm and recreational

      COMPLEX SOLUTIONS

      Trickier situations

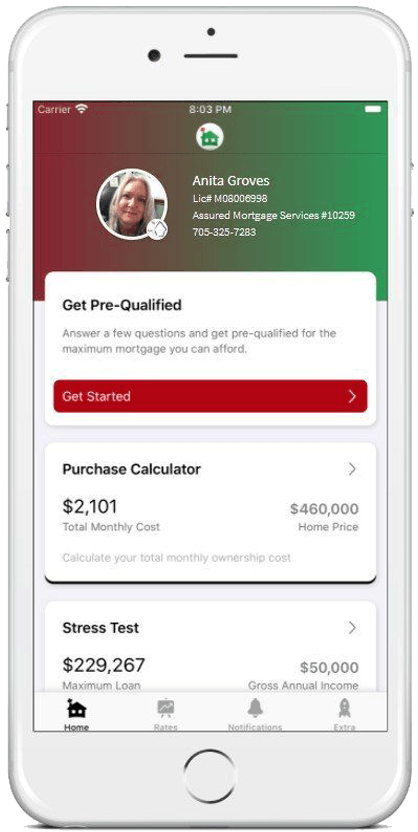
        Download the Canadian Mortgage App and:


        • Calculate your total cost of owning a home
        • Estimate the minimum down payment you need
        • Calculate Land transfer taxes and the available rebates
        • Calculate the maximum loan you can borrow
        • Stress test your mortgage
        • Estimate your Closing costs
        • Compare your options side by side
        • Search for the best mortgage rates
        • Email Summary reports (PDF)
        • Use my app in English, French, Spanish, Hindi and Chinese

        Found the cottage? Let's find out how to finance it.

        Send me the details before you make an offer. A short call now tells you which kind of cottage you are dealing with and what to expect, and there is no cost to find out.

        Call or text 705·325·7283 · 773 Atherley Road, Orillia, ON

        Articles To keep you informed

        Resources
        By Anita Groves • October 14, 2026
        You’ve outgrown your current home. It no longer fits your life, so moving makes sense. And you’re not interested in juggling two properties. Selling first and buying something new feels like the right move. Ideally, you want possession of the new home before leaving the old one. That overlap makes moving easier, reduces stress, and gives you time to paint, renovate, or settle in before the boxes arrive. But there’s a common challenge. What if the down payment for your next home is tied up in the equity of the one you’re selling? That’s where bridge financing comes in. How bridge financing works Bridge financing temporarily unlocks equity from your current home once it has a firm sale . It bridges the gap between selling your existing property and purchasing your next one, allowing you to use that equity toward your down payment. What about competitive markets? In a hot market, a strong offer often means a larger deposit . If you don’t have that cash sitting in your account, but you do have equity, a deposit loan can help you compete with confidence. The non-negotiable requirement To qualify for bridge financing or a deposit loan, your current home must have a firm, unconditional sale . No firm sale = no bridge or deposit loan. Lenders need certainty to calculate available equity and manage risk. Bottom line A firm sale is the key that unlocks bridge financing and deposit loans. If you’re planning a move and want to understand how these options could work for you, let’s talk. I’m always happy to walk you through your options and help you plan your next step with confidence.
        By Anita Groves • October 7, 2026
        Financial setbacks happen. Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future. Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward. What lenders look at after a bankruptcy or consumer proposal How long it’s been since your discharge Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then. Your credit rebuild Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly. To be considered fully re-established, lenders typically want to see: Two active trade lines At least two years of clean payment history Credit limits of around $2,500 on each No late or missed payments Your down payment or equity The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options. Your debt service ratios Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify. Conventional vs. insured mortgage options To access the most competitive mortgage products, lenders typically want to see: At least two years plus one day since discharge Fully re-established credit Minimum down payment requirements met Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty) Total debt obligations generally not exceeding 44% of your gross income Alternative lending options Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help. Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward. While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt. Let’s talk about your next step Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available. If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.
        By Anita Groves • September 30, 2026
        Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.
        Show More

        CONTACT US


        Contact Us

        GET IN TOUCH


        We're committed to helping you in any way we can.

        Leave us a note and we'll get in touch with you shortly.

        Phone or Text: 705-325-7283

        TF Phone or Fax: 877-256-7283

        CONTACT US


        Contact Us

        GET IN TOUCH


        We're committed to helping you in any way we can. Leave us a note and we'll get in touch with you shortly.

        Phone or Text: 705-325-7283

        TF Phone or Fax: 877-256-7283