Mortgage broker in Gravenhurst and Muskoka

Gravenhurst is the gateway to Muskoka, and cottage country comes with its own kind of mortgage. I have spent more than 25 years arranging financing across the area, from year-round homes in town to waterfront cottages on the lakes, and I work with lenders who actually understand recreational property.

How I help homeowners in Gravenhurst and Muskoka

Financing a cottage or waterfront property is not the same as a home in the city. Access, seasonality, water frontage, whether a place is winterized, and how it is used all matter to lenders, and many banks are cautious about them. I know which lenders are comfortable with these properties, so your cottage or acreage is judged fairly.

Who I work with in Gravenhurst and Muskoka

I help buyers purchasing a first cottage or a second property, owners refinancing to renovate or winterize, retirees accessing equity in a home they have owned for years, and people financing rural and recreational properties that do not fit a standard mortgage. When a property is unusual, that is often where I can help most.

Solutions people here ask about most

area served nearby

Gravenhurst Bracebridge Bala Torrance The Muskoka Lakes Savern Bridge Surrounding area

Local FAQ 

  • Can I get a mortgage on a seasonal or water-access cottage?

    Sometimes, yes. It depends on the property, but I work with lenders who consider recreational and seasonal properties that many banks will not.

  • Do you help buyers from out of town buying in Muskoka?

    Yes. Many cottage buyers come from the GTA and beyond, and I can handle everything by phone, email and online.
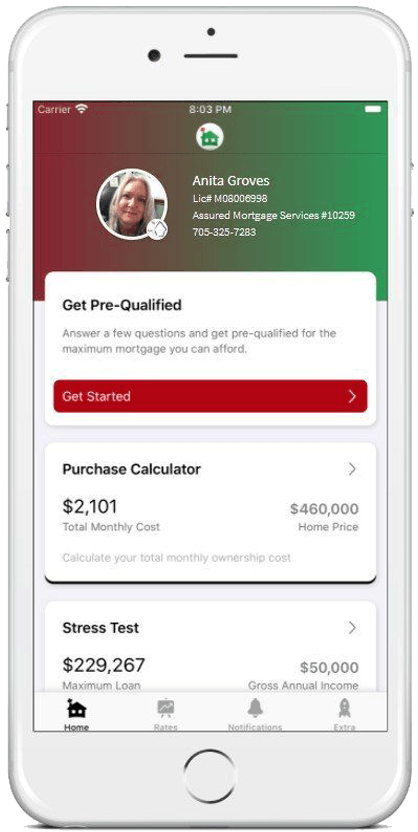
Download the Canadian Mortgage App and:


  • Calculate your total cost of owning a home
  • Estimate the minimum down payment you need
  • Calculate Land transfer taxes and the available rebates
  • Calculate the maximum loan you can borrow
  • Stress test your mortgage
  • Estimate your Closing costs
  • Compare your options side by side
  • Search for the best mortgage rates
  • Email Summary reports (PDF)
  • Use my app in English, French, Spanish, Hindi and Chinese

Let's talk about your situation.

The first conversation is free and there is no obligation.

Call or text 705-325-7283, or send me a question and I will get back to you.

Call or text 705·325·7283 · 773 Atherley Road, Orillia, ON

Articles To keep you informed

Resources
By Anita Groves September 9, 2026
When you apply for a mortgage, your employment history and status carry a lot of weight. Even if you feel secure in your job, lenders need proof that your income is reliable and will continue. To them, your employment status is one of the strongest indicators of whether you can make your mortgage payments long term. Here’s how lenders typically view different employment situations: Permanent Employment This is the gold standard. Once you’ve passed any probationary period and hold permanent status, lenders see you as a lower risk. It shows that your employer is committed to you, and your income is steady. Probationary Periods If you’re still on probation—usually 3 to 6 months, though sometimes longer—lenders may hesitate. That’s because your employer can end your contract without cause during this period. Once probation is over, you’re considered more secure. That said, context matters. If you’ve worked with the same company for years as a contractor and just transitioned into full-time employment, lenders may accept a letter from your employer confirming that probation is waived. Documentation is key here. Parental Leave Being on or about to take parental leave doesn’t mean you can’t qualify for a mortgage. As long as you have a letter from your employer guaranteeing your position and return-to-work date, lenders can use your regular salary—not your leave income—when assessing your application. Term Contracts This is one of the trickiest categories. Even highly skilled professionals with strong incomes can face challenges here. A term contract has a start and end date, which makes lenders question the stability of your future income. To use term-contract income, lenders generally want to see at least two years of history, or proof that your contract has already been renewed. The more evidence you can show of consistent employment, the stronger your case will be. The Bottom Line If you’re planning to apply for a mortgage, it’s important to understand how your employment status could affect your approval. Whether you’re starting a new job, coming back from leave, or working under contract, lenders want documentation that proves your income is reliable. 📞 If you’ve recently changed jobs or are planning a career shift, let’s connect. I can help you prepare your file so you qualify with confidence and avoid surprises in the approval process.
Smiling couple stands by a window, looking outside in a bright room
By Anita Groves September 4, 2026
Reverse mortgages let homeowners 55 and older access equity without selling. Here is an honest look at how they work, who they suit, and the tradeoffs.
By Anita Groves September 2, 2026
The Bank of Canada announced today that it is holding its target for the overnight rate at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. While Canada's economic recovery is broadening, a new layer of uncertainty has entered the picture. Here is what happened and what it means for your mortgage.
Show More

CONTACT US


Contact Us

GET IN TOUCH


We're committed to helping you in any way we can.

Leave us a note and we'll get in touch with you shortly.

Phone or Text: 705-325-7283

TF Phone or Fax: 877-256-7283

CONTACT US


Contact Us

GET IN TOUCH


We're committed to helping you in any way we can. Leave us a note and we'll get in touch with you shortly.

Phone or Text: 705-325-7283

TF Phone or Fax: 877-256-7283