Mortgage broker in Orillia

My office is right here in Orillia on Atherley Road, and I have spent more than 25 years helping people in this community get mortgages. Whether you are buying your first home near downtown, refinancing a place by Lake Couchiching, or working through a situation your bank could not help with, I will walk you through your options in plain language.

How I help homeowners in Orillia

Orillia is a real mix of established family neighbourhoods, waterfront homes, and rural and acreage properties just outside town in Severn and Oro-Medonte. That variety is one reason a local broker helps. I know the kinds of properties and situations that come up here, and I work with a wide range of lenders, from the big banks and credit unions to alternative and private lenders, so I can match the right one to you.

Who I work with in Orillia

A lot of my Orillia clients are self-employed: tradespeople, small business owners and seasonal workers whose income does not always fit a bank's checklist. I also help retirees looking to access their home equity, families consolidating debt, and buyers who were turned down elsewhere. If your situation feels complicated, that is exactly the kind of work I do.

area served nearby

Orillia Coldwater Washago Severn Ramara Oro-Medonte Surrounding townships

Local FAQ 

  • Do you have an office in Orillia?

    Yes. I am based on Atherley Road in Orillia and work with clients across the area in person, by phone and online.

  • Can you help if my bank in Orillia turned me down?

    Often, yes. A decline usually means your situation did not fit that one lender. I work with many lenders and can look for one that fits.
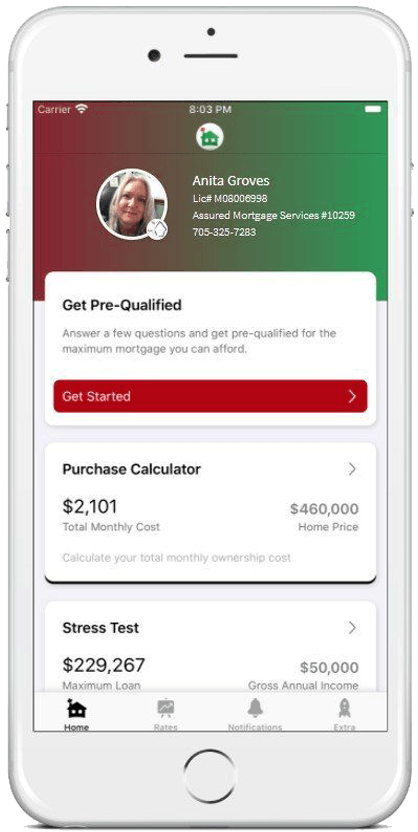
Download the Canadian Mortgage App and:


  • Calculate your total cost of owning a home
  • Estimate the minimum down payment you need
  • Calculate Land transfer taxes and the available rebates
  • Calculate the maximum loan you can borrow
  • Stress test your mortgage
  • Estimate your Closing costs
  • Compare your options side by side
  • Search for the best mortgage rates
  • Email Summary reports (PDF)
  • Use my app in English, French, Spanish, Hindi and Chinese

Let's talk about your situation.

The first conversation is free and there is no obligation.

Call or text 705-325-7283, or send me a question and I will get back to you.

Call or text 705·325·7283 · 773 Atherley Road, Orillia, ON

Articles To keep you informed

Resources

By Anita Groves • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Anita Groves • October 21, 2026
If the title of this article caught your attention, chances are your family is growing. Congratulations. If you’re thinking now is the right time to move into a home that better fits your growing family—but you’re unsure how parental leave affects your ability to qualify for a mortgage—you’re in the right place. Here’s the good news. Qualifying for a mortgage while on parental leave is possible when it’s done correctly. When you work with an independent mortgage professional, lenders can often qualify you based on your return-to-work income , as long as you can provide documentation confirming you have guaranteed employment waiting for you. A word of caution If you walk into a bank branch and disclose that you’re currently on parental leave, there’s a chance the bank will only allow you to qualify using your parental leave income. That can significantly reduce your borrowing power. Parental leave income is typically limited to 55% of your previous earnings, up to a weekly maximum. Qualifying on that amount alone can restrict your options and impact the type of home you can purchase. Why lender choice matters One of the biggest advantages of working with an independent mortgage professional is choice . You’re not limited to one lender’s rules or products. Some lenders will allow you to qualify using 100% of your confirmed return-to-work income , which can make a meaningful difference in your approval amount and overall options. What you’ll need to qualify Most lenders will require an employment letter that includes: Employer name (preferably on company letterhead) Your job title Original start date (to confirm probation has been completed) Confirmed return-to-work date Guaranteed salary upon return Lenders want reassurance that your income will resume once parental leave ends. You may also be asked to provide income history from the past couple of years, which is standard for most mortgage applications. One important note Whether or not you actually return to work after parental leave is entirely your decision. From a mortgage perspective, qualification is based on having a confirmed position available to you at the time of approval. If you have questions about qualifying for a mortgage while on parental leave—or anything mortgage-related—please connect anytime. I’d be happy to walk you through your options and help you plan with confidence.
By Anita Groves • October 14, 2026
You’ve outgrown your current home. It no longer fits your life, so moving makes sense. And you’re not interested in juggling two properties. Selling first and buying something new feels like the right move. Ideally, you want possession of the new home before leaving the old one. That overlap makes moving easier, reduces stress, and gives you time to paint, renovate, or settle in before the boxes arrive. But there’s a common challenge. What if the down payment for your next home is tied up in the equity of the one you’re selling? That’s where bridge financing comes in. How bridge financing works Bridge financing temporarily unlocks equity from your current home once it has a firm sale . It bridges the gap between selling your existing property and purchasing your next one, allowing you to use that equity toward your down payment. What about competitive markets? In a hot market, a strong offer often means a larger deposit . If you don’t have that cash sitting in your account, but you do have equity, a deposit loan can help you compete with confidence. The non-negotiable requirement To qualify for bridge financing or a deposit loan, your current home must have a firm, unconditional sale . No firm sale = no bridge or deposit loan. Lenders need certainty to calculate available equity and manage risk. Bottom line A firm sale is the key that unlocks bridge financing and deposit loans. If you’re planning a move and want to understand how these options could work for you, let’s talk. I’m always happy to walk you through your options and help you plan your next step with confidence.
Show More

CONTACT US


Contact Us

GET IN TOUCH


We're committed to helping you in any way we can.

Leave us a note and we'll get in touch with you shortly.

Phone or Text: 705-325-7283

TF Phone or Fax: 877-256-7283

CONTACT US


Contact Us

GET IN TOUCH


We're committed to helping you in any way we can. Leave us a note and we'll get in touch with you shortly.

Phone or Text: 705-325-7283

TF Phone or Fax: 877-256-7283